Stable Home Prices in 2027 Depend on Business Investment Outpacing Slower Population Growth
In the second quarter of 2026, Canadian companies spent more on machinery and equipment than at any point since the spring of 2024, and their spending on computers and peripherals jumped 16.7%, by Statistics Canada's count. Few people shopping for a house noticed. They were watching rates and immigration numbers.
Those two numbers explain the last few years. The next one will be decided by something quieter: whether businesses invest enough to create the incomes that replace the demand slower population growth is taking away. National Bank's chief economist Stéfane Marion says prices could begin stabilizing in 2027 as mortgage rates approach their peak, and he points to business investment as the force that could bring demand back. If you're weighing a purchase, a move up or a rental property in the Fraser Valley, that's the variable your decision actually rests on.
Why fewer newcomers doesn't settle the 2027 question
Ottawa has cut temporary resident targets, and population growth has slowed on purpose. That eases pressure on rentals and starter homes. It also removes the easiest source of demand the market has had for a decade, because a growing population fills units almost regardless of what people earn.
Without that tailwind, every sale needs a buyer with enough income to borrow. The market stops counting heads and starts counting people who qualify. CREA put the national average price at $666,538 in September 2026. That price holds only if enough households can carry the mortgage behind it, and carrying it comes down to steady, rising pay.
How business investment turns into buyers who can qualify
When a company buys new equipment or software, it usually expects each worker to produce more. Over time that supports higher wages and more secure jobs, and lenders reward secure income.
The stress test shows why the link is so direct. Under OSFI's rules you must qualify at the higher of your contract rate plus 2 percentage points or 5.25%. As an illustration, a borrower offered 4.5% has to show they can handle payments at 6.5%. A raise or a move into a better-paying role changes what that household can borrow far more than a small rate cut would.
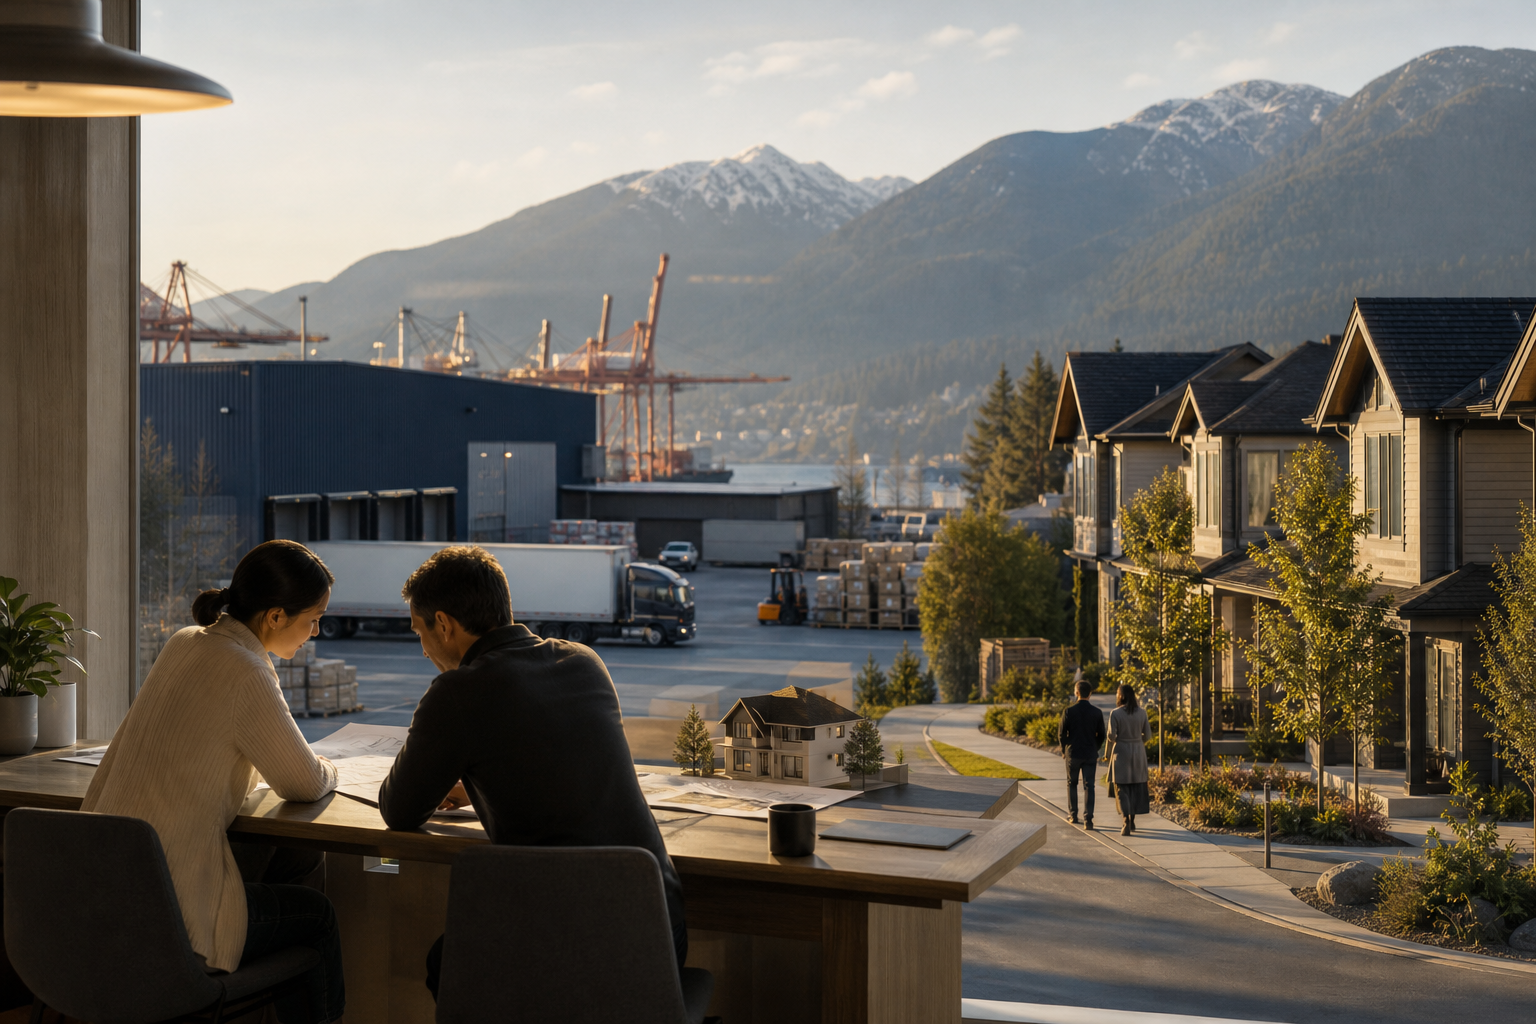
That's also why the current market is holding together. British Columbia's mortgage delinquency rate was 0.25% in the first quarter of 2026, even after a wave of renewals from the low-rate years of 2020 and 2021. People with stable jobs keep paying. In Abbotsford, where agriculture, manufacturing and tech-adjacent employers anchor the economy, local employment is shaping prices more than Vancouver spillover does. Detached homes here still offer relatively better value for move-up buyers, and that gap lasts only as long as the paycheques behind it.
What to check before you buy, move up or refinance
You can't control national investment figures, but you can apply the same logic to your own file:
Run your numbers at the stress-test rate. Take your expected contract rate, add 2 points (or use 5.25% if that's higher), and see whether the payment still fits your budget after a renewal.
Judge the income behind the home. For your own purchase, that's your job security over the next five years. For a rental, look at who employs your likely tenants and whether those employers are hiring or investing locally.
Decide on need rather than a rate forecast. Some economists see rates near their peak, but a plateau can last longer than expected. If you need more space, or need to restructure debt to improve cash flow, plan around what you can qualify for today.
When 2027 arrives, the forecast that matters most for your home is the one about your own income and the employers around you.

In the second quarter of 2026, Canadian companies spent more on machinery and equipment than at any point since the spring of 2024, and their spending on computers and peripherals jumped 16.7%, by Statistics Canada's count. Few people shopping for a house noticed. They were watching rates and immigration numbers.
Those two numbers explain the last few years. The next one will be decided by something quieter: whether businesses invest enough to create the incomes that replace the demand slower population growth is taking away. National Bank's chief economist Stéfane Marion says prices could begin stabilizing in 2027 as mortgage rates approach their peak, and he points to business investment as the force that could bring demand back. If you're weighing a purchase, a move up or a rental property in the Fraser Valley, that's the variable your decision actually rests on.
Why fewer newcomers doesn't settle the 2027 question
Ottawa has cut temporary resident targets, and population growth has slowed on purpose. That eases pressure on rentals and starter homes. It also removes the easiest source of demand the market has had for a decade, because a growing population fills units almost regardless of what people earn.
Without that tailwind, every sale needs a buyer with enough income to borrow. The market stops counting heads and starts counting people who qualify. CREA put the national average price at $666,538 in September 2026. That price holds only if enough households can carry the mortgage behind it, and carrying it comes down to steady, rising pay.
How business investment turns into buyers who can qualify
When a company buys new equipment or software, it usually expects each worker to produce more. Over time that supports higher wages and more secure jobs, and lenders reward secure income.
The stress test shows why the link is so direct. Under OSFI's rules you must qualify at the higher of your contract rate plus 2 percentage points or 5.25%. As an illustration, a borrower offered 4.5% has to show they can handle payments at 6.5%. A raise or a move into a better-paying role changes what that household can borrow far more than a small rate cut would.
That's also why the current market is holding together. British Columbia's mortgage delinquency rate was 0.25% in the first quarter of 2026, even after a wave of renewals from the low-rate years of 2020 and 2021. People with stable jobs keep paying. In Abbotsford, where agriculture, manufacturing and tech-adjacent employers anchor the economy, local employment is shaping prices more than Vancouver spillover does. Detached homes here still offer relatively better value for move-up buyers, and that gap lasts only as long as the paycheques behind it.
What to check before you buy, move up or refinance
You can't control national investment figures, but you can apply the same logic to your own file:
When 2027 arrives, the forecast that matters most for your home is the one about your own income and the employers around you.
Sources
Read Next
The Bank of Canada Didn't Raise Your Fixed Rate. Bond Traders Did.
Why the Lowest Mortgage Rate Often Costs Move-Up Buyers the Most
Canada's 500,000-Homes-a-Year Goal Depends on Fixing the Apprenticeship Pipeline
Markets Expect an October 28 Rate Cut. Your Mortgage Plan Shouldn't.